[wp_tech_share]

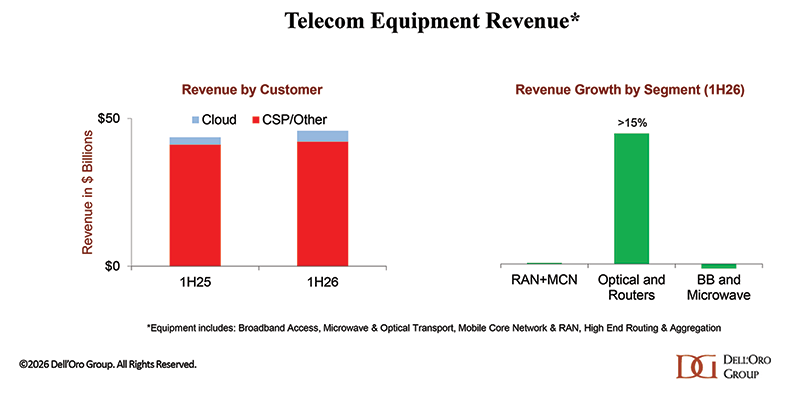
The positive momentum that shaped the telecom equipment market in 2025 extended into the first half of 2026. Preliminary findings suggest that aggregate worldwide telecom equipment revenues across the six programs tracked by the Dell’Oro Group—Broadband Access, Microwave & Optical Transport, Mobile Core Network (MCN), Radio Access Network (RAN), and High End Routing & Aggregation—increased 5% year-over-year (Y/Y) in 1H26, marking a sixth consecutive quarter of Y/Y growth. This follows the 4% increase recorded in 2025, when the market returned to growth following a 14% revenue decline between 2022 and 2024. While the 2025 recovery reflected a combination of inventory normalization, easier comparisons, improving wireless and wireline demand, and increased cloud investment, the composition of growth shifted in 1H26 toward markets with greater exposure to AI and data center infrastructure.

While traditional communication service providers (CSPs) continue to account for the vast majority of telecom equipment revenues (>90%), cloud providers are playing an increasingly important role in driving incremental growth. We estimate that cloud providers accounted for 55% of the revenue growth in 1H26, reflecting continued investment in AI and data center infrastructure and the connectivity required to support it.

The impact of this investment wave varies significantly by technology. Our analysis shows that 1H26 growth was concentrated in Optical Transport and High End Routers, the two segments most directly exposed to cloud and data center infrastructure investments. Optical Transport revenue increased at a double-digit pace, supported by strong demand for data center interconnect, while the High End Routing & Aggregation market benefited from robust activity across both cloud providers and CSPs. In contrast, aggregate RAN and MCN revenues were relatively stable, as were Broadband Access and Microwave Transmission.

Regional dynamics were also favorable outside of China. North America, EMEA, CALA, and Asia Pacific excluding China all contributed to the 1H26 expansion, while conditions in China remained more challenging. North America continued to benefit disproportionately from AI and cloud-related infrastructure investments, including strong demand for optical transport, routing, and fiber access equipment. China, meanwhile, is tracking below our expectations as infrastructure spending continues to shift from traditional telecom networks toward compute infrastructure—the top 3 CSPs in China are collectively targeting 40% growth in computing capex in 2026, while traditional connectivity capex is expected to decline 24%.

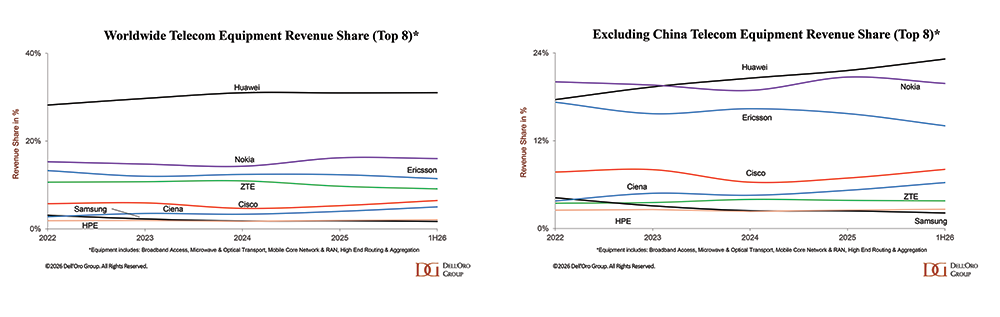
Global supplier dynamics remained relatively stable in the first half. Huawei was the largest telecom equipment supplier worldwide, followed by Nokia and Ericsson. Outside China, however, share movements were more notable. Huawei and Cisco gained share in 1H26 relative to 2025, while Ericsson and Nokia’s combined revenue share declined by about three percentage points. The shifts partly reflect differences in supplier exposure to the faster-growing optical and routing markets, as well as regional market dynamics.

Looking ahead, the analyst team remains positive about the market trajectory. Worldwide revenues across the six programs are projected to increase 3% to 5% in 2026, up from 2% to 4% in the previous update. Meanwhile, the risk profile has evolved somewhat. China is trending below full-year expectations, while rising memory and component costs have moved higher on the list of second-half concerns. These headwinds are being balanced by continued strength in cloud and AI-related infrastructure investment.

[wp_tech_share]
Musk, Satellites and the Future of the RAN

Elon Musk wants a bigger piece of the connectivity market. It is not clear how big a piece he wants, what the challenges are, or what his ambitions mean for mobile network operators (MNOs) and the terrestrial RAN market.

Recent commentary has become more ambitious. SpaceX estimates the addressable connectivity market opportunity is worth around $1.6 T, including $870 B for Starlink Broadband and $740 B for Starlink Mobile, consistent with the communications service providers (CSPs) revenue data published in the Dell’Oro Telecom Capex report minus devices and China, or roughly $8 ARPU for nearly 8 B users. More recently, SpaceX management has made clear that its goals extend beyond filling coverage gaps from space. In its 2Q earnings call, the company said it plans to build terrestrial infrastructure to complement its non-terrestrial network, potentially using large numbers of femto cells/small base stations deployed alongside Starlink terminals. The intention is not just to position for future growth opportunities but also to win more of the traditional carrier business – Starlink specifically called out the $0.6 T of revenue in the US.


Why would Elon Musk want to enter the CSP and MNO business in the first place?

Musk is widely considered one of the most successful entrepreneurs/visionaries of this era. He has already had three home runs with EVs, rockets, and satellites, with Physical AI and autonomous vehicles (AVs) among his next targets—all ultimately connected to his larger ambition of multiplanetary living. The traditional MNO market—with slow growth, high barriers to entry, enormous capital requirements, and roughly 10% net margins—does not look like a missing piece in this puzzle. How does connectivity fit into the bigger picture?

Understanding why SpaceX entered the satellite communications business in the first place is a good place to start.  After all, Starlink was not the first attempt to use satellites to disrupt terrestrial communications. The 1990s produced multiple LEO ventures, including Iridium, Globalstar, and Teledesic—the technology worked, but the economics did not. Investments turned into bankruptcies and abandoned broadband plans. The first LEO boom demonstrated that global coverage from space was technically possible. However, it did not demonstrate that it could be delivered economically at scale.

By controlling the rockets, SpaceX entered the game with a solid foundation. Falcon 9 and booster reuse changed the economics and ultimately allowed Starlink to build a constellation of 11K+ satellites with favorable capex relative to previous attempts, paving the way for Starlink becoming not just an important engineering pillar but also a vital economic engine­ for Musk’s bigger vision. Musk has previously stated that revenue from the satellite network could ultimately help finance a city on Mars.

That background may also help explain SpaceX’s growing ambitions in mobile. Becoming another conventional CSP or MNO is unlikely the primary objective. Musk has repeatedly moved vertically when an external dependency becomes strategically important or when controlling another layer changes the economics. Rockets enabled Starlink, Starlink extended SpaceX into global communications, and D2D is now extending that reach directly to the smartphone.

From a connectivity perspective, Starlink addresses the geographic limitations with terrestrial RAN. While 4G currently covers around 90% of the global population per Ericsson’s Mobility Report, some estimates suggest geographic coverage is around 15% (per ChatGPT). Terrestrial mobile networks are extremely efficient where people are concentrated, but the math becomes less favorable as population density falls. Satellites work the opposite way, providing coverage almost regardless of where people—or machines—happen to be. What may have started primarily as a way to connect the unconnected has consequently expanded from rural broadband to ships, aircraft, enterprises, and now the smartphone.
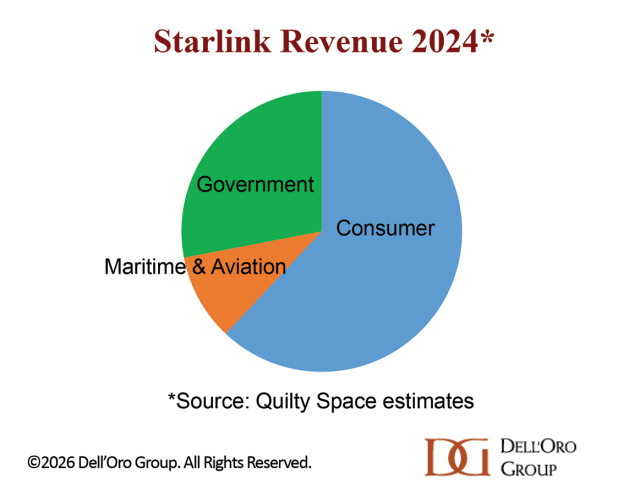
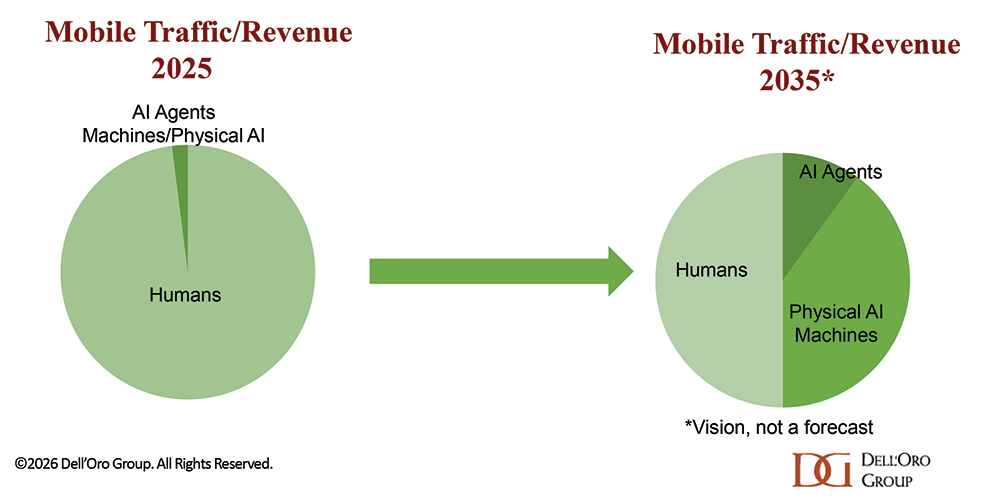
The strategic value of that capability could increase further in a world increasingly shaped by AI and physical AI. Today’s mobile network is designed and dimensioned for humans carrying smartphones, with most traffic and revenue ultimately generated by people consuming video, social media, and other applications. But in a world increasingly populated by AI agents, autonomous vehicles, robots, drones, and other forms of physical AI, human-driven traffic may eventually represent only one portion of the connectivity opportunity. Unlike humans, these machines might not remain concentrated within the existing cellular footprint. The traffic profile and ratios between indoor/outdoor, uplink/downlink, day/night, and dense/rural coverage could evolve if non-human-originated traffic comprises a larger share of overall mobile traffic, especially if Musk is right that these machines/robots will consume significantly more cellular traffic than humans using smartphones. Please note we don’t have a 2035 end-user forecast split for humans, AI agents, and machines—the illustration is more of a vision showing the three large buckets.
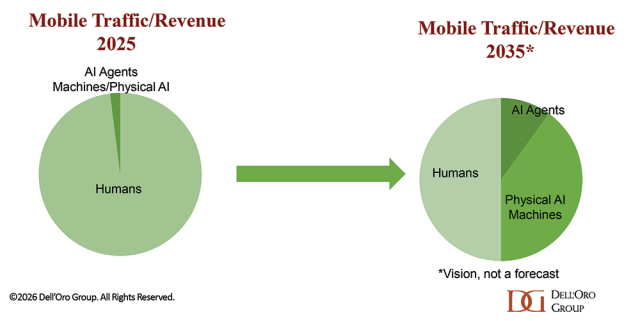
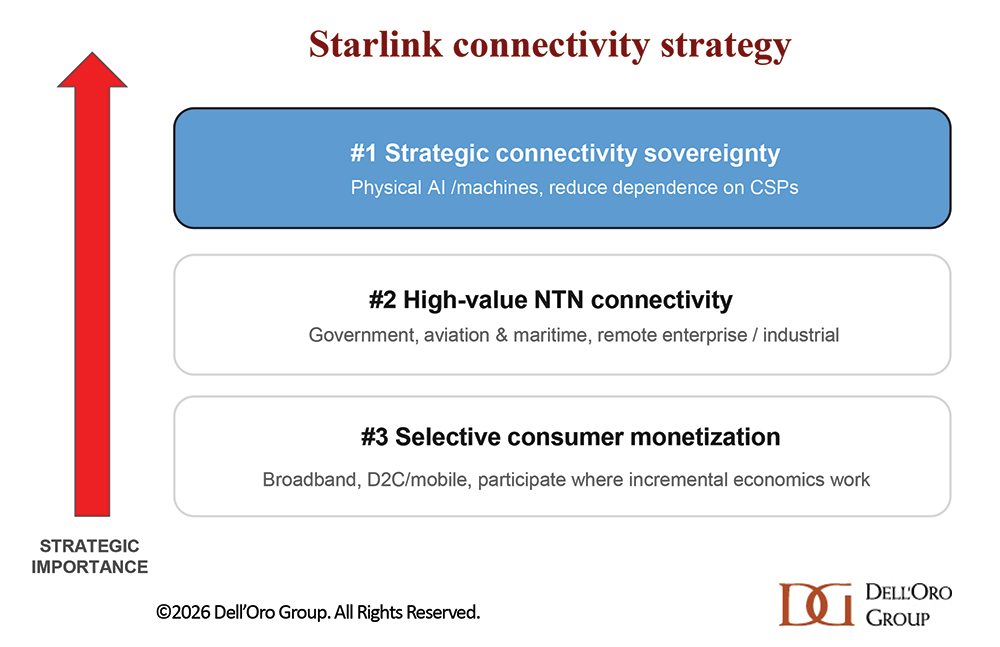
Viewed through that lens, Musk may care less about capturing another smartphone subscriber scrolling Instagram in Stockholm and much more about ensuring that a Tesla, Optimus robot, autonomous truck, drone, or some yet-to-be-invented AI-powered machine can remain connected wherever it operates. The recent push into D2D connectivity, mobile spectrum, and potentially terrestrial infrastructure therefore looks less like an attempt to build another conventional MNO and more like the gradual assembly of an end-to-end connectivity platform spanning terrestrial and non-terrestrial networks. Ubiquitous connectivity may simply be critical infrastructure for the AI and machine-driven world Musk is envisioning—and, as with rockets, batteries, charging, and AI, another strategic dependency he is increasingly unwilling to leave entirely in someone else’s hands.
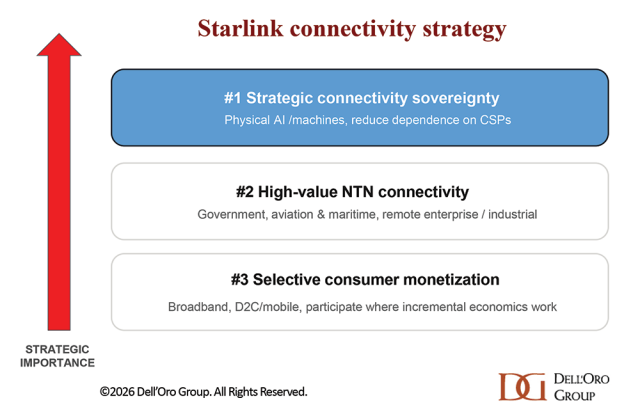
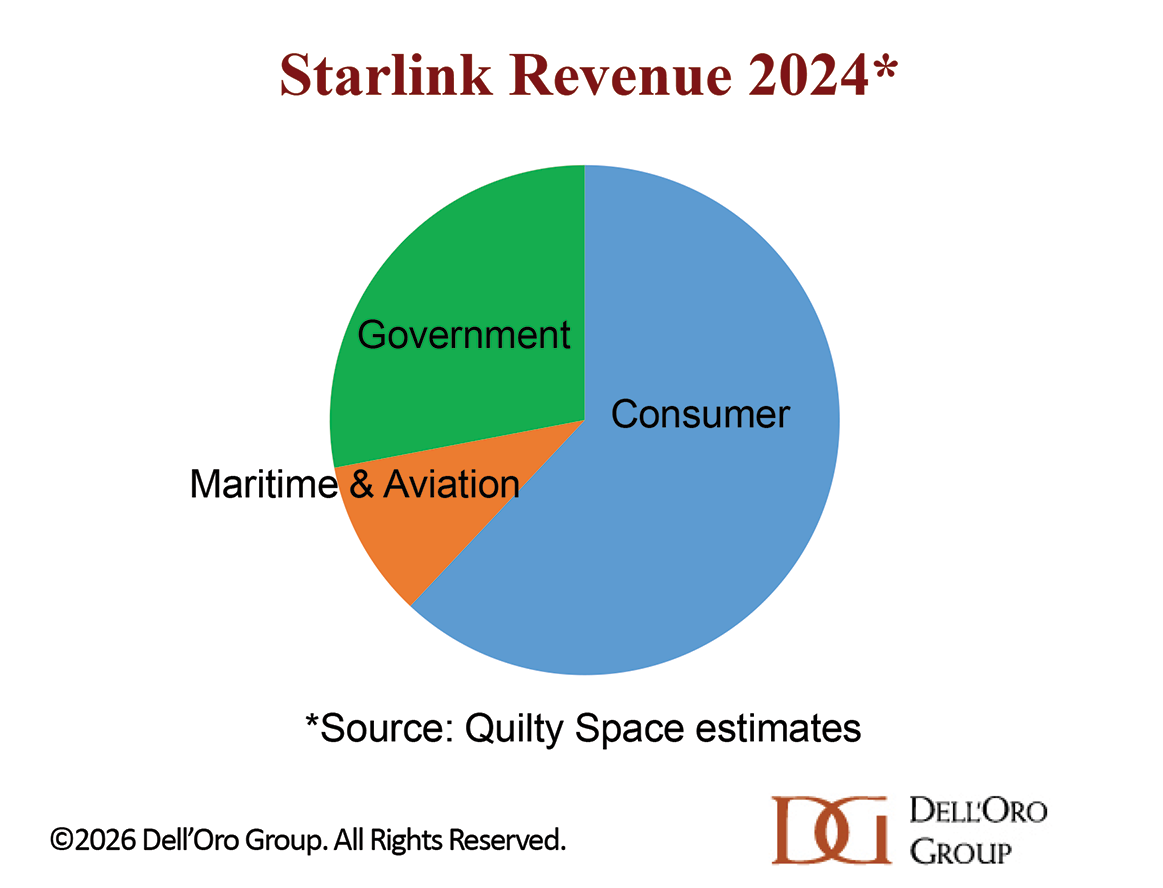
Strategic connectivity sovereignty does not mean SpaceX will ignore attractive commercial opportunities. The economics of satellite connectivity are already compelling in segments such as aviation, maritime, government, and remote enterprise/industrial, where terrestrial alternatives can be expensive or unavailable. And just as MNOs have learned to monetize excess mobile capacity with FWA, Starlink can selectively pursue consumer and enterprise opportunities where the incremental economics make sense.

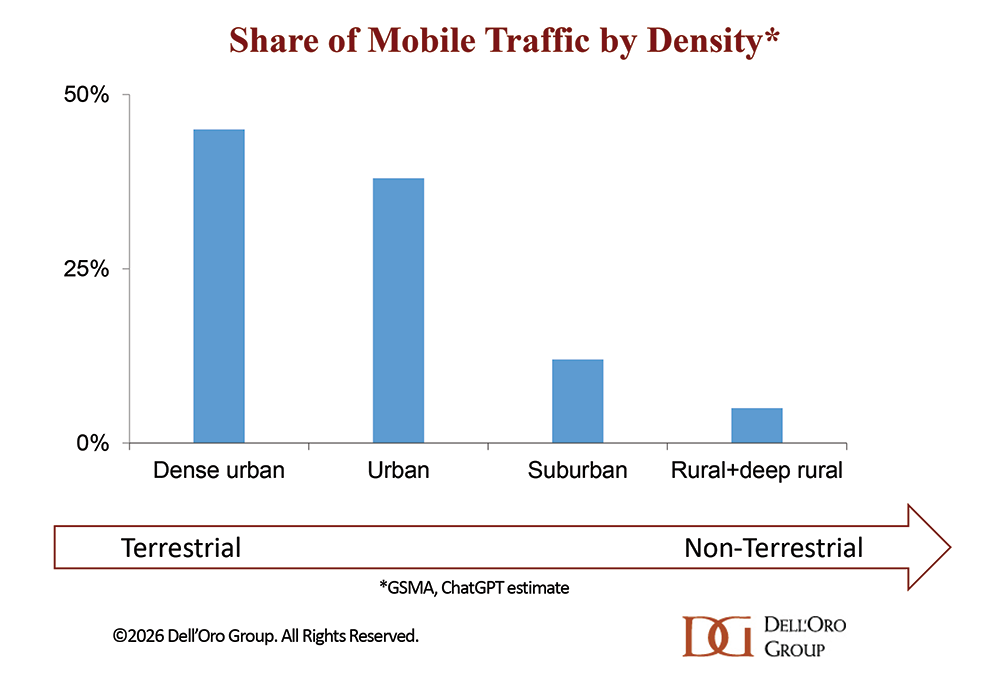
Ultimately, the addressable opportunity will vary enormously by density and geography: terrestrial optimizes capacity per km², while NTN optimizes geographic coverage.


What are the challenges?

If Musk’s ambition is to create a more ubiquitous connectivity platform spanning terrestrial and non-terrestrial networks, the fundamental question is – what are the big roadblocks? And the challenges are significant. At a high level, we can group them into three buckets: physics, assets, and ecosystem.

Physics is important. Even if Musk has an impressive track record of proving naysayers wrong and has already taken satellites much further than almost everyone thought possible, this can’t be overlooked in the world of wireless. Physics and the resulting economic challenges are the primary reason small cells and mmWave 5G did not live up to the initial hype.

Satellites are extraordinarily effective at solving the coverage problem — according to Sebastian Barros’ Telecom Newsletter, Starlink’s ~11 K operational satellites currently cover roughly 95% of the world’s landmass and maritime zones. But coverage and capacity are not the same. Terrestrial mobile networks achieve enormous capacity by dividing the network into increasingly smaller cells and repeatedly reusing the same spectrum.

A satellite beam covers a much larger geographic area, making the same degree of spectrum reuse difficult. This means the challenge is not aggregate capacity but capacity density. Satellite networks can spread enormous amounts of capacity across the globe, but mobile traffic is highly concentrated geographically. A terabit of unused capacity over sparsely populated areas cannot relieve a congested network in Tokyo or New York. Terrestrial RAN solves this problem through extreme spatial reuse, concentrating spectrum and capacity precisely where demand occurs. Satellites cannot replicate that density nearly as efficiently.

The link budget is also inherently asymmetric. SpaceX can put larger antennas and more power on its satellites, but it cannot change the antenna, transmit power, or battery constraints of an ordinary smartphone. Consequently, satellite connectivity can potentially eliminate many of the world’s remaining coverage gaps, but it is much harder to see satellites economically absorbing the enormous traffic generated in dense urban and suburban areas.

In other words, geographic coverage is SpaceX’s advantage while capacity density remains terrestrial RAN’s advantage. This is also why SpaceX’s terrestrial ambitions matter. If Musk wants more than coverage—if he ultimately wants a meaningful share of total mobile traffic, here defined to include humans and machines operating indoors and outdoors—he will undoubtedly need terrestrial radios as well.
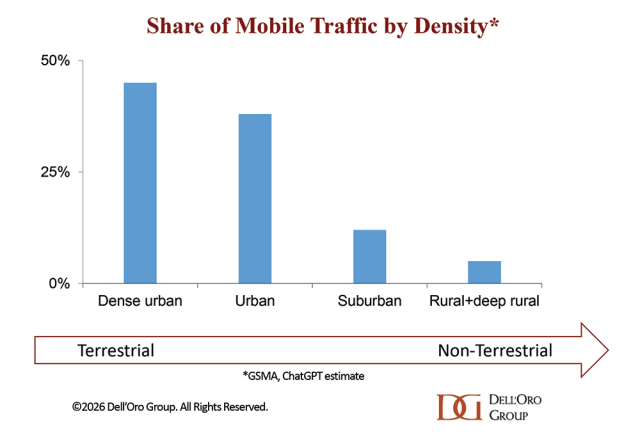
That leads to the second challenge: spectrum and terrestrial infrastructure. SpaceX’s spectrum acquisitions materially improve its position, but building a competitive mobile network requires more than owning some spectrum and small cells. The incumbent MNOs have spent decades accumulating spectrum across multiple bands and deploying hundreds of thousands of macro sites engineered around propagation, capacity, interference, mobility, and indoor coverage. SpaceX is exploring whether it can address this cost structure differently, potentially deploying large numbers of small base stations alongside existing Starlink terminals and using the Starlink network for backhaul.

The concept is interesting because most current mobile traffic is consumed indoors, so if this works, it could complement the existing macro network. While it is early days and we haven’t had a chance to talk to Starlink about this concept yet, one challenge could be overlap—Starlink terminals are currently located where customers need satellite broadband, not necessarily where a mobile network needs capacity. In addition, they still need to figure out RF planning, indoor coverage, handovers, and interference—these steps don’t disappear just because the ratios between small cells and macros change. Spectrum itself remains scarce and heavily regulated. Ultimately, the deeper SpaceX moves into terrestrial mobile, the more it will face the same physical, regulatory, and economic constraints that have shaped the traditional mobile infrastructure market.

The ecosystem is another major challenge. The incumbent operators already have the spectrum, sites, fiber, customers, devices, distribution, roaming relationships, regulatory infrastructure, and operational experience required to deliver mobile service at scale. They can also respond collectively, whether through standards, roaming arrangements, spectrum partnerships, or alliances with competing satellite providers. Mobile connectivity involves far more than transporting bits—authentication, seamless mobility, voice, emergency services, device certification, billing, customer support, and roaming all need to work reliably. Regulation could also impact Starlink’s ability to operate a mobile network in some countries.

None of these challenges suggests that SpaceX cannot become a meaningful force in mobile connectivity. But they do suggest that replacing the terrestrial mobile network is a very different proposition from complementing it. Satellites give SpaceX an enormous structural advantage in geographic coverage, while the terrestrial incumbents retain an equally important advantage in capacity density, spectrum depth, infrastructure, and ecosystem. The more interesting question, therefore, may not be whether SpaceX can replace the MNOs or terrestrial RAN. Ultimately, the key question is how far they can go with their existing assets and how much further they want to go – where is the sweet spot?


Impact on RAN

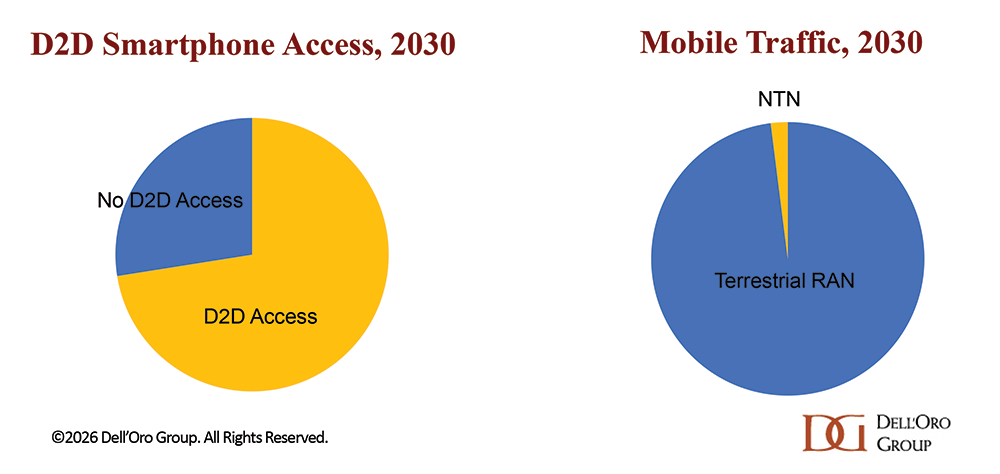
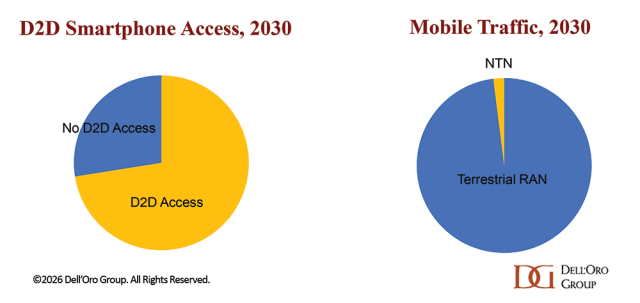
Our long-term position remains unchanged—we continue to believe that NTNs are highly important complements to today’s terrestrial RAN networks and the future is hybrid. But we need to separate the “addressable D2D smartphone opportunity” from the “addressable mobile traffic share.” The base case is that D2D will scale rapidly and most smartphones outside of China will eventually have access to satellite D2D connectivity. At the same time, physics won’t change. And since the base case is that mobile traffic (human plus machine) will grow at a 17% CAGR over the next five years with human-driven traffic still dominating (Ericsson Mobility Report), the mid-point scenario is for terrestrial RAN to carry more than 98% of the overall global mobile traffic by 2030.

Alternative outcomes are likely, especially if we extend the forecast horizon. Two significant swing factors include the mobile traffic share of physical AI/machines in outdoor settings and the reach of Starlink’s terrestrial ambitions.

If physical AI accelerates faster than expected and traffic patterns/profiles are more conducive to satellite connectivity, the overall NTN share could surprise to the upside.  Similarly, if Physical AI develops more slowly than expected, the traffic split between terrestrial and NTN could differ.

The physics favor terrestrial RAN for capacity and NTN for geographic coverage, and that won’t change. But Musk has a history of changing the economics around the physics.
[wp_tech_share]

Nokia’s latest AI-RAN announcement is more about increased confidence and improved messaging than a fundamental change in strategy. The AI-RAN roadmap and timeline remain largely unchanged, but Nokia has refined its migration story, sharpened its focus on software-driven innovation, and provided additional insight into how it views AI-RAN’s role in addressing operator challenges and strengthening its competitive position in the evolving RAN market.

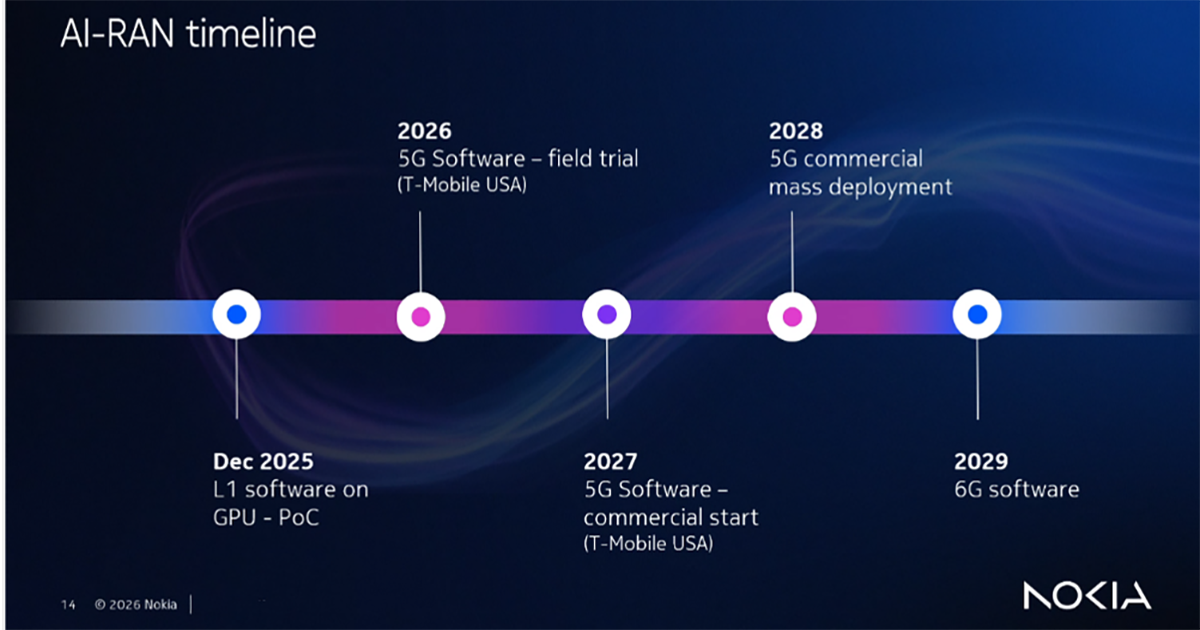
Nokia’s AI-RAN roadmap and timeline remain broadly unchanged. The AI-RAN roadmap and timeline are largely unchanged from what the company shared with analysts and investors over the past year, suggesting Nokia is executing against an existing strategy rather than introducing a new one.

Source: Nokia


The migration path has been refined and simplified. Compared with last year’s Nokia-NVIDIA framework—which highlighted purpose-built D-RAN, D-RAN vRAN, and C-RAN vRAN—the company has simplified the way it presents deployment options. Nokia is now placing less emphasis on specific vRAN architectures and more emphasis on deployment flexibility and performance profiles (installed-base leverage, high-capacity AI-RAN, and cloud-native AI-RAN). Broadly speaking, the migration strategy remains intact, with the changes reflecting refinements in packaging and messaging rather than a fundamental shift in direction.

Nokia is becoming more confident in its merchant silicon/GPU-based AI-RAN strategy. The most notable changes are in messaging and conviction. There was more hedging at MWC Barcelona when analysts pressed them on their 6G R&D efforts between custom and merchant silicon. Now, Nokia appears increasingly confident in its merchant silicon/GPU-based approach and is positioning AI-RAN as a software-defined platform strategy rather than a hardware story. While the company continues to support multiple hardware options, management indicated that most future software innovation and feature development will target the merchant silicon track.

AI-on-RAN is also becoming more tangible. Beyond AI-for-RAN use cases, Nokia is now highlighting sensing, positioning/location services, and third-party software applications that could run on the platform. Importantly, these are being positioned as complementary software-ecosystem opportunities rather than as the primary justification for the architecture.

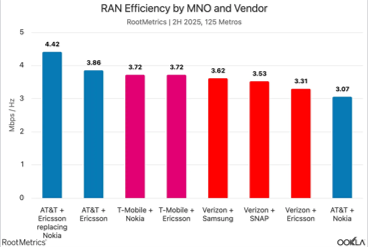
The 2x spectral efficiency claim is compelling but requires more context.The headline claim of up to 2x spectral efficiency improvements is compelling, especially since the gains appear to exceed those highlighted in other AI-RAN announcements. At the same time, it should be viewed with some caution until there is greater clarity around the underlying assumptions, benchmarks, and how it compares with competing approaches from Huawei, Ericsson, and others in actual deployments. Spectral efficiency remains highly dependent on deployment scenarios and starting points, making cross-vendor comparisons difficult. Hopefully, Ookla can update this RAN efficiency chart by 2028.


Source: Ookla


The announcement supports Dell’Oro’s AI-RAN and GPU-RAN forecasts. More broadly, the announcement is consistent with our recently published $35 B AI-RAN forecast and our upward revision to the GPU-RAN outlook, which now exceeds $1 B by 2030. Nokia’s emphasis on AI-for-RAN as the primary value proposition, combined with its growing confidence in merchant silicon-based deployments, is consistent with our view that AI-for-RAN adoption is accelerating as operators prepare for more software-centric and AI-native RAN architectures.

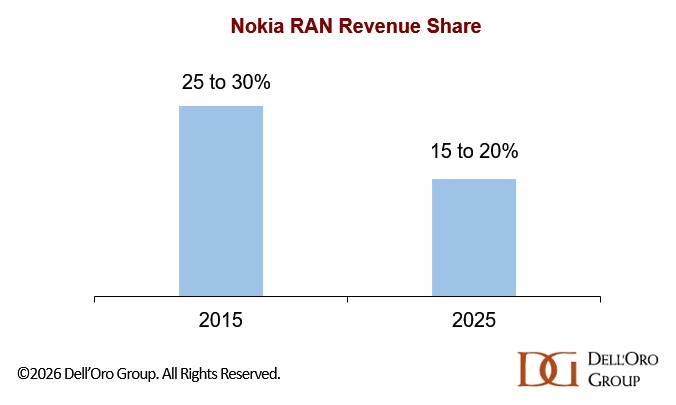
AI-RAN is strategically important to Nokia’s broader RAN turnaround efforts. Finally, Nokia’s AI-RAN strategy should be viewed in the context of its broader RAN turnaround efforts. Having lost approximately 10 percentage points of RAN market share over the past decade, Nokia is well aware of the importance of maintaining sufficient scale in the highly concentrated RAN market. AI RAN is therefore more than a technology roadmap—it represents a strategic bet that software-driven innovation, flexible deployment options and AI-native capabilities can help strengthen Nokia’s competitive position over the long term. The latest announcement signals that Nokia is becoming increasingly confident that AI-native RAN will play a central role in its efforts to improve its competitive standing in the RAN market.

[wp_tech_share]

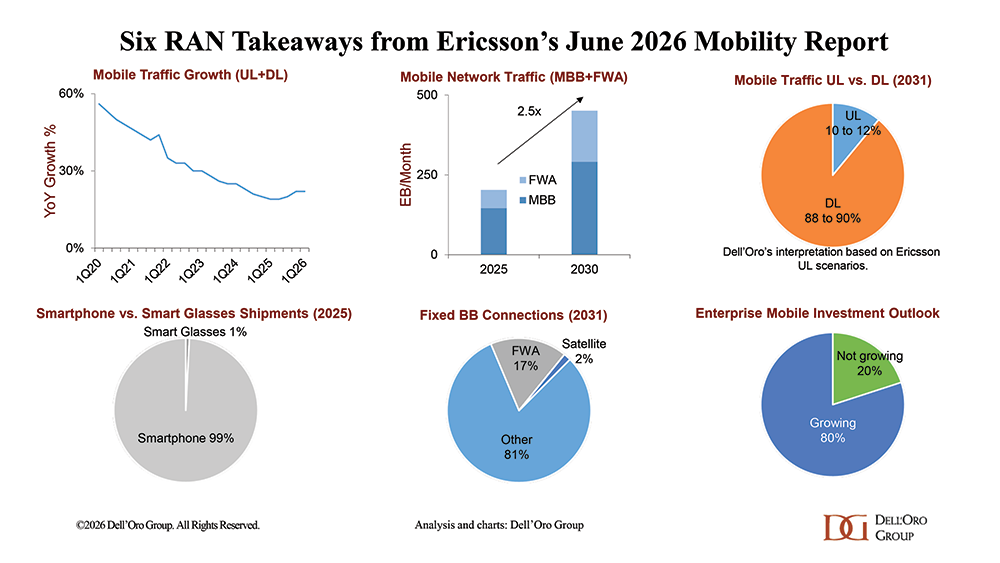
Ericsson’s Mobility Report provides a comprehensive overview of the end-user trends shaping the RAN market. The report is loaded with data and insights. Below are six takeaways we are keeping in mind at Dell’Oro Group as we update our 5-year RAN forecast.

22% mobile traffic growth in 1Q26

Mobile traffic growth continues to moderate. Given concerns that traffic growth could decelerate more quickly than expected, it is encouraging that total mobile network traffic has now posted seven consecutive quarters of stable year-over-year growth in the 20% to 22% range. While growth rates are no longer at the elevated levels seen in the early days of 5G, traffic demand is growing and continues to support long-term RAN capacity investments.


Total traffic to grow 2.5x by 2030

Ericsson projects total mobile network traffic (mobile broadband and FWA) to increase by approximately 2.5x between 2025 and 2030, implying roughly 20% annual growth. This outlook influences not only the timing of 6G deployments but also the level of capacity investments during the second half of the 5G cycle. Even as the industry is trying to pivot towards network differentiation and the Uplink (UL), the relationship with RAN revenue and the overall mobile traffic growth is expected to improve, especially as the industry is now in somewhat uncharted territories when it comes to the supply/demand of mobile connectivity.


UL 10% to 12% of total traffic

For years, suppliers have emphasized the importance of improving UL performance. First, it was short-form video, and now AI-driven applications are expected to further increase UL demand. Even so, our interpretation of Ericsson’s medium- and high-UL scenarios is that UL traffic will still account for only about 10% to 12% of total mobile network traffic by 2031, up from roughly 8% today. AI may significantly reshape traffic patterns, but Downlink (DL) traffic will continue to dominate overall network demand.


10 M smart glasses in 2025

The projected growth in mobile traffic continues to be overwhelmingly driven by smartphones. Although expectations are rising that smart glasses could become the next major connected device category, Ericsson estimates shipments reached approximately 10 million units in 2025—roughly 1% of smartphone shipments. The figure is an important reminder that while the long-term opportunity is compelling, adoption remains in its early stages, and the base case is that smartphones will continue to dominate mobile traffic for the foreseeable future. 


Satellite accounts for 2% of fixed connections

Even as Starlink and other satellite providers continue to expand their ambitions across home broadband, enterprise networking, and mobile connectivity, Ericsson projects satellite broadband will account for about 2% of global fixed broadband connections by 2031. In comparison, Fixed Wireless Access (FWA) is expected to represent approximately 17% of fixed broadband connections, reinforcing that terrestrial wireless technologies remain the much larger opportunity. 


80% of enterprises are growing their mobile investments

Private wireless increased 16% and accounted for 3 to 5% of total RAN revenue in 2025. To date, the primary driver has been industrial 4G and 5G deployments supporting applications where Wi-Fi or public cellular networks cannot meet performance, coverage, or mobility requirements. Looking ahead, Ericsson’s survey of more than 100 enterprise decision makers across North America, Europe, and Asia suggests that 80% plan to increase their mobile investments, in part to help scale AI initiatives. While private wireless remains a relatively small portion of the RAN market today, enterprise demand continues to strengthen.

In other words, AI continues to dominate industry discussions; however, the latest Ericsson Mobility Report reinforces that the RAN market over the next five years will still be driven primarily by steady traffic growth, smartphones, FWA, and enterprise investment. AI is expected to increase UL requirements and create new network demands, but the fundamental traffic drivers remain largely unchanged.

[wp_tech_share]
What Market Share Says About Börje Ekholm’s Legacy

Leadership transitions often invite instant verdicts. But as the Wallenberg family noted during Ericsson’s previous leadership transition, turnarounds in the telecom space are measured in decades rather than quarters. As Ericsson enters a new chapter, it is still too early to fully assess the long-term impact of Börje Ekholm’s strategic decisions. What we can evaluate today, however, is how Ericsson’s competitive position in the telecom equipment and Radio Access Network (RAN) markets evolved during his tenure.

Market share is not a perfect measure of success. It says little about profitability, shareholder returns, or the quality of strategic investments. Still, it remains one of the clearest indicators of whether customers continued to choose Ericsson in an intensely competitive market.


From Decline to Stability

When Ekholm became CEO in early 2017, Ericsson was emerging from a challenging period. The company had experienced deteriorating profitability, multiple restructuring programs, and significant losses in its RAN revenue share.

We estimate that Ericsson lost approximately 10 percentage points (PPs) of global RAN revenue share between 2011 and 2016, in part due to an intensified competitive landscape. Reversing that trend would not be trivial.

While Ericsson did not dramatically increase its global market position over the next decade, it largely succeeded in reversing the negative momentum that characterized the years leading up to 2017.

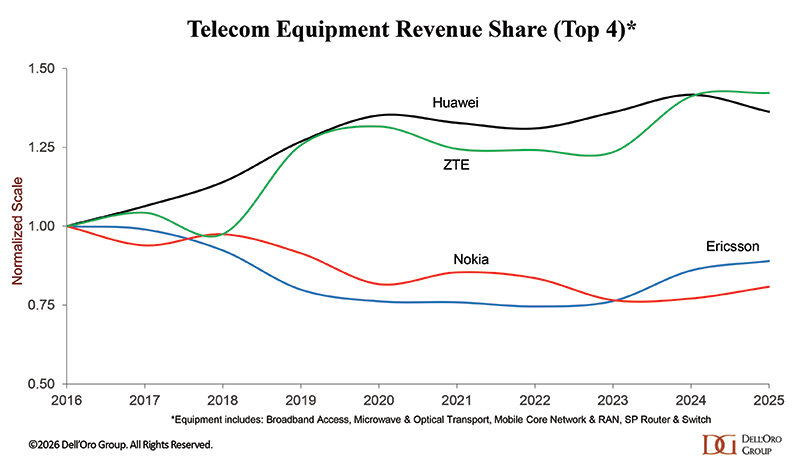
Our preliminary analysis suggests Ericsson’s overall telecom equipment revenue share declined by one to two percentage points between 2016 and 2025, settling at roughly 15% of the worldwide telecom equipment market in 2025. Considering the significant changes affecting the industry—including geopolitical shifts, supply chain disruptions, and the 5G investment cycle—this represents a fairly stable competitive position.

DellOro-Telecom Equipment Revenue Share Chart


Looking Beyond the Headlines

At first glance, Huawei appears to be the clear winner of the past decade. Among the largest suppliers, Huawei and ZTE posted the strongest relative market share gains, increasing their telecom equipment positions across the six telecom programs tracked by the Dell’Oro Group by roughly 40% between 2016 and 2025.

Ericsson’s trajectory looks different. Instead of pursuing aggressive share gains across the broader telecom equipment market, Ericsson largely defended its position. Ericsson’s wireless focus is key. Wireless infrastructure has consistently represented nearly half of the telecom equipment market, making leadership in RAN strategically more important than expanding into adjacent segments.


The RAN Picture is More Favorable

The picture becomes even more interesting when focusing specifically on RAN.

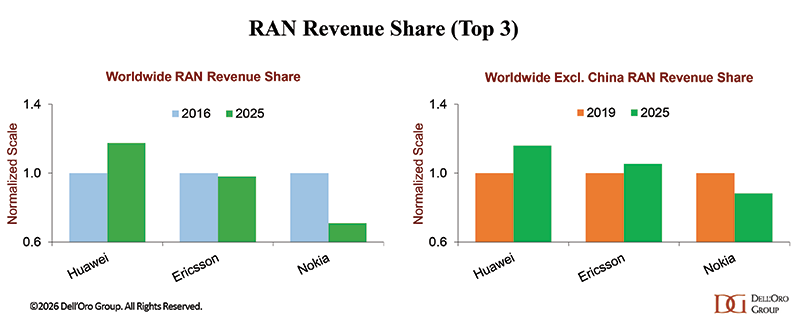
Globally, Ericsson’s RAN revenue share has remained relatively stable in the 25% to 30% range throughout most of Ekholm’s tenure. This stands in sharp contrast to the steep losses experienced between 2011 and 2016.

Meanwhile, Nokia experienced a more pronounced decline over the same period, while Huawei continued strengthening its global leadership position. Stability may not generate headlines, but in a mature infrastructure market dominated by a handful of global suppliers, maintaining share can be an important achievement.

DellOro - RAN Revenue Share Chart


The China Impact

Any assessment of Ericsson’s market position should also consider regional dynamics.

China has become increasingly difficult for foreign vendors, particularly amid geopolitical tensions and reciprocal restrictions affecting telecom infrastructure procurement—we estimate Ericsson and Nokia’s combined RAN revenue share in China has declined by 11 PPs between 2019 and 2025. As a result, global market share figures understate Ericsson’s competitive performance in many of its core markets.

Excluding China, Ericsson’s position actually improved between 2019 and 2025, gaining approximately four percentage points of RAN market share. Huawei also gained share outside China, while Nokia lost ground.

It is also worth noting that the US has played an outsized role in Ericsson’s RAN performance. In fact, if we normalize for both China and North America, Ericsson’s RAN share is stable while Huawei and Nokia are up.


Market Share Is Only One Part of the Story

Of course, market share does not provide the full picture.

Investors will also judge the period based on profitability, shareholder returns, and the success of strategic initiatives such as the enterprise expansion and the Vonage acquisition. Some of these initiatives remain works in progress, and their long-term value may not be fully understood for years.

Nevertheless, market share provides an objective scorecard. By that measure, Ericsson appears to have successfully halted a long-running decline, maintained its RAN leadership position, and strengthened its standing in some markets outside China.


Looking Ahead

The next CEO will inherit a company facing new challenges. Mobile data traffic growth is slowing, and operator capital spending is moderating. And within the capex mix, operators are shifting focus toward areas more closely tied to the data center wave, creating a double headwind for suppliers that remain more dependent on wireless infrastructure. AI is on the rise in network operations and in the RAN. And the role of SW is evolving. 6G is on the horizon, but cumulative 6G RAN revenue in the first six years of its cycle is projected to be 10% to 20% lower than the comparable period in the 5G cycle.

At the same time, Per Narvinger will inherit a company whose competitive foundation is considerably more stable than it was in 2017. While the industry appears to be changing faster today than it did when Börje took over, and some believe Ericsson has missed the data center wave, I get the impression that Ericsson is more confident in its position and prospects today than it was when Börje began.

That may ultimately become one of Börje Ekholm’s most long-lasting contributions. At the end of the day, he may be remembered less for any single metric—whether RAN market share, profitability, or shareholder returns—and more for restoring Ericsson’s competitiveness and preserving its position among the world’s leading telecom infrastructure suppliers.