[wp_tech_share]

I attended Mplify’s member summit in Boston several weeks ago, where I also served as a judge for its NaaS awards. One theme stood out: enterprise networking and security are becoming more integrated, yet delivering that integration across the broader communications service provider industry remains surprisingly difficult. Technology providers are combining capabilities enterprises historically bought separately, while communications service providers are working to make their networks and operational systems function as a coordinated ecosystem.

Both efforts are moving toward the same objective: making enterprise networking and security simpler to consume and operate. In my Distributed Cloud Networking (DCN) research at Dell’Oro Group, this tension is becoming increasingly important. The question is not whether Network-as-a-Service (NaaS) will evolve beyond connectivity. It already is. The more interesting question is whether the industry can deliver an integrated experience without forcing enterprises to rely on a single technology provider.

Four observations from Boston stand out.
The Networking and Security Stack Is Converging, but Innovation Is Far from Over

In my DCN research, I look at the enterprise WAN through three interconnected domains: the user/WAN edge, WAN middle mile, and cloud/application edge. Each has traditionally been served by different technologies and vendors. SASE and SD-WAN address secure user and branch connectivity, WAN-as-a-Service brings greater flexibility and programmability to the middle mile, and multi-cloud networking extends connectivity and security controls closer to distributed applications and workloads.

The boundaries between these domains are becoming less rigid. Convergence is happening horizontally as providers extend their capabilities across the three domains, and vertically as networking, security, observability, and automation become more tightly integrated. For some enterprises, this creates an opportunity to collapse a complicated networking and security stack into a more unified operating model, with fewer control planes, fewer integration points, and more consistent policy enforcement.

However, convergence should not be mistaken for the end of specialization. Significant innovation continues within each domain, and some of the more interesting developments are happening outside the traditional SASE conversation. The WAN middle mile, for example, is gaining renewed importance as enterprises look to dynamically connect private data centers, public clouds, AI factories, and emerging neocloud providers. At the cloud edge, application-aware networking and security continue to evolve, while SASE vendors are extending beyond traditional user-to-application traffic into broader infrastructure use cases.

AI is accelerating these developments, but it did not create the underlying challenges. Cloud adoption, distributed workforces, and application decentralization were already reshaping enterprise networking. AI adds urgency through more dynamic workloads, distributed inference, and new requirements for data governance and security. The important takeaway is that the market is still innovating within individual domains even as the broader technology stack converges.


Two Paths Toward a Simpler Enterprise Experience

One response to these market dynamics is technology convergence. Providers are extending their capabilities across traditional product boundaries to deliver more networking and security functions through a common platform. The appeal is understandable: enterprises increasingly want consistent policy, visibility, and operational control across users, branches, cloud environments, and applications. A more integrated provider can potentially reduce the complexity of making those pieces work together.

However, there is another path: a federated ecosystem of specialized technology and service providers. Not every enterprise wants to standardize on one vendor, nor will one vendor necessarily deliver the best capabilities across every domain. Existing investments, geographic requirements, specialized security needs, and heterogeneous application architectures will continue to create demand for best-of-breed solutions. The challenge is making those independent technologies behave like a coordinated service rather than a collection of individually managed products.

I do not see these approaches as mutually exclusive. Even highly integrated platforms depend on third-party connectivity and infrastructure to extend their reach. Likewise, a multi-provider ecosystem can offer customers a unified experience if the underlying integration is mature enough. This creates an interesting competitive dynamic: innovation within individual domains remains valuable, but the ability to integrate and operationalize those technologies becomes equally important.

In that sense, the real competition is not simply single-vendor versus multi-vendor. It is about which approach can deliver the required capabilities with the least operational friction, while preserving the flexibility enterprises need as their architectures evolve.


Boston Highlighted the Gap Between Federation and Execution

Federation was one of the strongest themes throughout Mplify’s Boston event. There was broad agreement that no single service provider can deliver every component of a global enterprise network, particularly as cloud and AI workloads become more geographically distributed. More importantly, several presentations showed that industry collaboration is moving beyond architecture diagrams into practical commercial workflows.

Bob Victor, Comcast Business’s Chief Product Officer and Mplify Board Chair, discussed efforts to connect Comcast and Colt’s automated workflows. Both companies have invested in internal automation, but transactions between them have historically involved spreadsheets and manual handoffs. Verizon described its use of Mplify’s Lifecycle Service Orchestration (LSO) Sonata APIs for wholesale transactions and its direction toward replacing legacy Access Service Request processes with standardized interfaces. Equinix and Comcast also discussed efforts to simplify service discovery and connectivity procurement through interconnected marketplaces.

These developments stand out because they show progress toward making independently operated networks function as a coordinated supply chain. However, the discussions also exposed a significant maturity gap between today’s implementations and the vision of fully automated, federated networking. Automating service discovery and quoting is not the same as automating end-to-end delivery. A provider may return a quote in seconds while installation, provisioning, troubleshooting, and performance assurance still depend on manual processes.

Legacy OSS/BSS environments, inconsistent operational data, and limited automation among smaller partners remain obstacles. There is also a commercial dimension that received welcome attention in Boston. Standardized interfaces do not automatically resolve contractual complexity, layers of reseller margin, service-level accountability, or ownership of the customer relationship. These are not secondary issues. They directly affect whether a multi-provider solution can compete with the simplicity an integrated platform promises.

This was one of my biggest takeaways from Boston. Federation requires business-model innovation alongside technical interoperability, and the industry still has considerable work to do on both fronts. The opportunity is significant, but getting multiple providers to communicate is only the first step toward making them operate as one.


Standardization Is Becoming More Important, Not Less

Having participated in standards efforts at the IETF and Trusted Computing Group, I appreciate the work required to build industry consensus and turn technical specifications into interoperable implementations. Standards do not eliminate competition or technological differentiation. Done well, they provide a common foundation on which companies can innovate without forcing customers into proprietary integration models.

This is why I view Mplify’s work as strategically important. The alliance has spent years developing Carrier Ethernet service definitions, LSO APIs, common product models, and certification programs. These assets are increasingly relevant as enterprises seek cloud-like consumption models across multiple communications service providers. Standardization also creates an opportunity for smaller and specialized providers to participate in larger ecosystems without having to build custom integrations for every commercial relationship.

Now Mplify is extending that work toward agentic automation and federation. Its LSO framework now supports the Model Context Protocol (MCP), and ongoing initiatives are developing reusable AI-agent capabilities, trusted provider discovery, and agent-to-agent coordination. The direction is promising because it builds on the existing service definitions, data models, and transaction workflows rather than assuming AI agents can independently solve the complexities of network operations.

In fact, AI may increase the importance of standardization. An agent that can discover and order connectivity is useful, but an agent that can reliably coordinate those actions across multiple providers while respecting commercial agreements, workflow sequencing, and security policies is far more valuable. Achieving that requires common definitions of services, authorization, operational states, and expected outcomes. It also requires mechanisms to verify that the agents and underlying systems behave as intended.

The industry is not there yet. The agentic federation vision remains ahead of broad production adoption, and considerable work remains on conventional service automation. Still, I see the effort as directionally constructive. The challenge for Mplify and its members will be translating the standards and architectural work into repeatable implementations that deliver measurable improvements in service delivery and operational efficiency.


What I Will Be Watching

The next phase of NaaS will be shaped by two related developments. First, how far can technology providers simplify enterprise networking through horizontal and vertical integration? Continued innovation across the user edge, middle mile, and cloud edge will create new possibilities, but comprehensive technology coverage does not automatically translate into a coherent operating model.

Second, how quickly can the broader service provider ecosystem close the interoperability gap? Mplify’s standards and certification work can help, but success ultimately depends on adoption, operational integration, and commercial execution. The strongest evidence of progress will not be another architectural framework or federation demonstration. It will be the ability to consistently discover, order, deliver, secure, and assure services across multiple providers without pushing the complexity back onto the enterprise.

For enterprises, the outcome matters more than the architecture. Integrated platforms can absorb more of the enterprise networking and security relationship, while specialized providers can preserve their differentiation by becoming easier to integrate and consume. I expect both models to remain relevant, with competitive advantage increasingly determined by how effectively providers turn their technology and partnerships into a simpler customer experience.

Boston reinforced my view that the future of NaaS is not solely about who can assemble the broadest networking and security stack. It is also about whether the industry can make a network assembled from multiple providers operate with the simplicity and accountability enterprises increasingly expect from a single platform. That is the opportunity Mplify is helping the industry pursue, and it is where much of the next chapter of enterprise WAN innovation remains to be written.
[wp_tech_share]
Musk, Satellites and the Future of the RAN

Elon Musk wants a bigger piece of the connectivity market. It is not clear how big a piece he wants, what the challenges are, or what his ambitions mean for mobile network operators (MNOs) and the terrestrial RAN market.

October 2026 Update: SpaceX’s agreement to acquire up to 14 MHz of 800 MHz spectrum strengthens its position in the terrestrial mobile market and reinforces its ambitions to compete more directly with incumbent operators. While the acquisition introduces additional possibilities for terrestrial RAN deployments, it does not materially change our five-year RAN market outlook. We have updated the analysis below to reflect the latest developments and clarify the potential direct and indirect implications for RAN equipment demand.

Recent commentary has become more ambitious. SpaceX estimates the addressable connectivity market opportunity is worth around $1.6 T, including $870 B for Starlink Broadband and $740 B for Starlink Mobile (consistent with the CSP revenue data published in the Dell’Oro capex report minus devices and China, or roughly $8 ARPU for nearly 8 B users).  More recently, SpaceX management has made clear that its goals extend beyond filling coverage gaps from space. In its 2Q earnings call, the company said it plans to build terrestrial infrastructure to complement its non-terrestrial network, potentially using large numbers of femto cells/small base stations deployed alongside Starlink terminals. The intention is not just to position for future growth opportunities but also to win more of the traditional carrier business – Starlink specifically called out the $0.6 T of revenue in the US.


Why would Elon Musk want to enter the CSP and MNO business in the first place?

Musk is widely considered one of the most successful entrepreneurs/visionaries of this era. He has already had three home runs with EVs, rockets, and satellites, with Physical AI and autonomous vehicles (AVs) among his next targets—all ultimately connected to his larger ambition of multiplanetary living. The traditional MNO market—with slow growth, high barriers to entry, enormous capital requirements, and roughly 10% net margins—does not look like a missing piece in this puzzle. How does connectivity fit into the bigger picture?

Understanding why SpaceX entered the satellite communications business in the first place is a good place to start.  After all, Starlink was not the first attempt to use satellites to disrupt terrestrial communications. The 1990s produced multiple LEO ventures, including Iridium, Globalstar, and Teledesic—the technology worked, but the economics did not. Investments turned into bankruptcies and abandoned broadband plans. The first LEO boom demonstrated that global coverage from space was technically possible. However, it did not demonstrate that it could be delivered economically at scale.

By controlling the rockets, SpaceX entered the game with a solid foundation. Falcon 9 and booster reuse changed the economics and ultimately allowed Starlink to build a constellation of 11K+ satellites with favorable capex relative to previous attempts, paving the way for Starlink becoming not just an important engineering pillar but also a vital economic engine­ for Musk’s bigger vision. Musk has previously stated that revenue from the satellite network could ultimately help finance a city on Mars.

That background may also help explain SpaceX’s growing ambitions in mobile. Becoming another conventional CSP or MNO is unlikely to be the primary objective. Musk has repeatedly moved vertically when an external dependency becomes strategically important or when controlling another layer changes the economics. Rockets enabled Starlink, Starlink extended SpaceX into global communications, and D2D is now extending that reach directly to the smartphone.

From a connectivity perspective, Starlink addresses the geographic limitations of terrestrial RAN. While 4G currently covers around 90% of the global population per Ericsson’s Mobility Report, some estimates suggest geographic coverage is around 15%. Terrestrial mobile networks are extremely efficient where people are concentrated, but the math becomes less favorable as population density falls. Satellites work the opposite way, providing coverage almost regardless of where people—or machines—happen to be. What may have started primarily as a way to connect the unconnected has consequently expanded from rural broadband to ships, aircraft, enterprises, and now the smartphone.

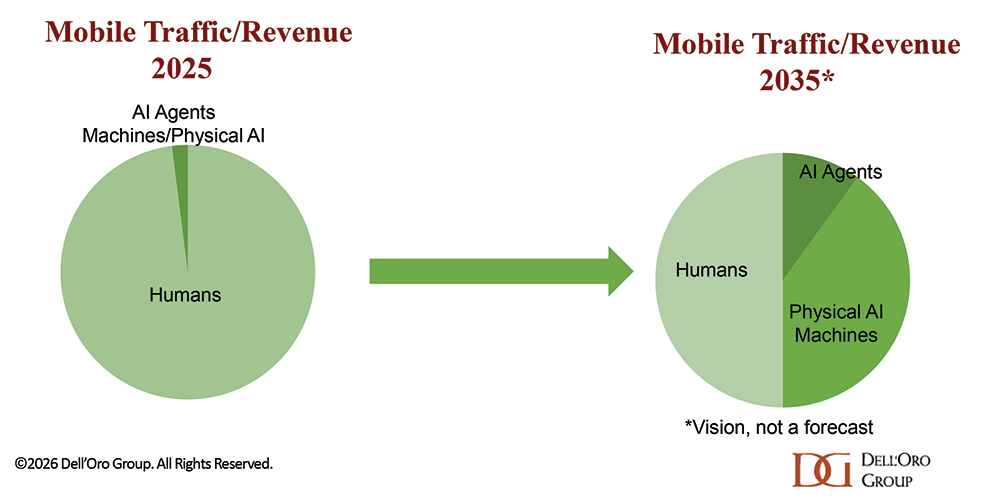
The strategic value of that capability could increase further in a world increasingly shaped by AI and physical AI. Today’s mobile network is designed and dimensioned for humans carrying smartphones, with most traffic and revenue ultimately generated by people consuming video, social media, and other applications. But in a world increasingly populated by AI agents, autonomous vehicles, robots, drones, and other forms of physical AI, human-driven traffic may eventually represent only one portion of the connectivity opportunity. Unlike humans, these machines might not remain concentrated within the existing cellular footprint. The traffic profile and ratios between indoor/outdoor, uplink/downlink, day/night, and dense/rural coverage could evolve if non-human-originated traffic comprises a larger share of overall mobile traffic, especially if Musk is right that these machines/robots will consume significantly more cellular traffic than humans using smartphones. Please note we don’t have a 2035 end-user forecast split for humans, AI agents, and machines—the illustration is more of a vision showing the three large buckets.

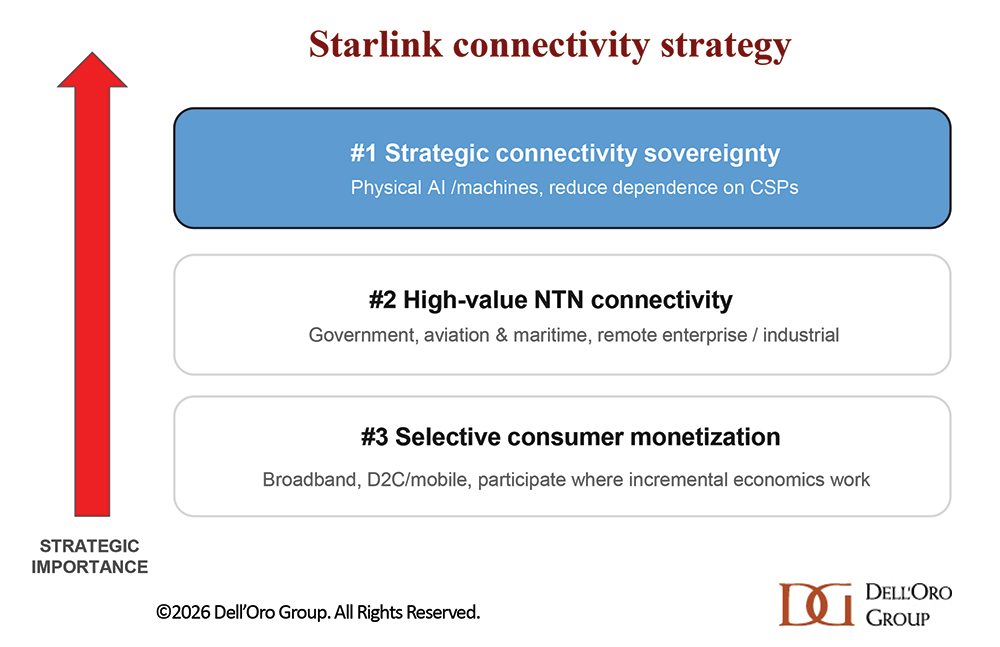
Viewed through that lens, Musk may care less about capturing another smartphone subscriber scrolling Instagram in Stockholm and much more about ensuring that a Tesla, Optimus robot, autonomous truck, drone, or some yet-to-be-invented AI-powered machine can remain connected wherever it operates. The recent push into D2D connectivity, mobile spectrum, and potentially terrestrial infrastructure therefore looks less like an attempt to build another conventional MNO and more like the gradual assembly of an end-to-end connectivity platform spanning terrestrial and non-terrestrial networks. Ubiquitous connectivity may simply be critical infrastructure for the AI and machine-driven world Musk is envisioning—and, as with rockets, batteries, charging, and AI, another strategic dependency he is increasingly unwilling to leave entirely in someone else’s hands.

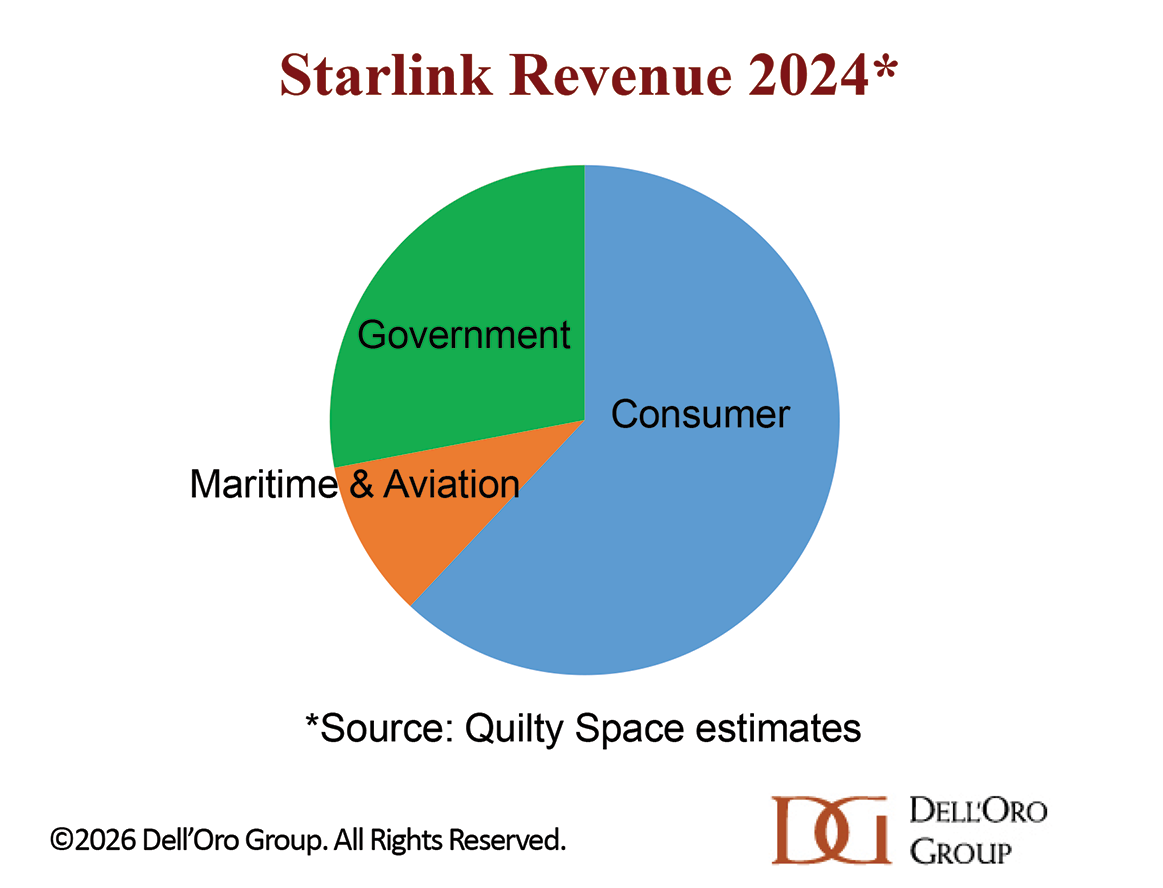
Strategic connectivity sovereignty does not mean SpaceX will ignore attractive commercial opportunities. The economics of satellite connectivity are already compelling in segments such as aviation, maritime, government, and remote enterprise/industrial, where terrestrial alternatives can be expensive or unavailable. And just as MNOs have learned to monetize excess mobile capacity with FWA, Starlink can selectively pursue consumer and enterprise opportunities where the incremental economics make sense.

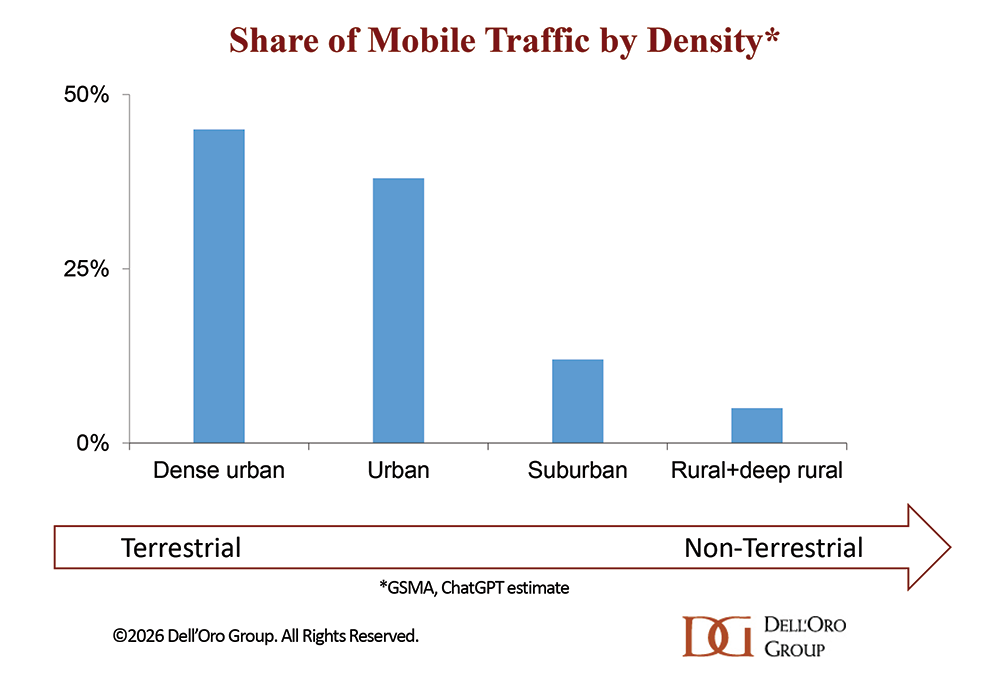
Ultimately, the addressable opportunity will vary enormously by density and geography: terrestrial optimizes capacity per km², while NTN optimizes geographic coverage.


What are the challenges?

If Musk’s ambition is to create a more ubiquitous connectivity platform spanning terrestrial and non-terrestrial networks, the fundamental question is – what are the big roadblocks? And the challenges are significant. At a high level, we can group them into three buckets: physics, assets, and ecosystem.

Physics is important. Even if Musk has an impressive track record of proving naysayers wrong and has already taken satellites much further than almost everyone thought possible, this can’t be overlooked in the world of wireless. Physics and the resulting economic challenges are the primary reason small cells and mmWave 5G did not live up to the initial hype.

Satellites are extraordinarily effective at solving the coverage problem — according to Sebastian Barros’ Telecom Newsletter, Starlink’s ~11 K operational satellites currently cover roughly 95% of the world’s landmass and maritime zones. But coverage and capacity are not the same. Terrestrial mobile networks achieve enormous capacity by dividing the network into increasingly smaller cells and repeatedly reusing the same spectrum.

A satellite beam covers a much larger geographic area, making the same degree of spectrum reuse difficult. This means the challenge is not aggregate capacity but capacity density. Satellite networks can spread enormous amounts of capacity across the globe, but mobile traffic is highly concentrated geographically. A terabit of unused capacity over sparsely populated areas cannot relieve a congested network in Tokyo or New York. Terrestrial RAN solves this problem through extreme spatial reuse, concentrating spectrum and capacity precisely where demand occurs. Satellites cannot replicate that density nearly as efficiently.

The link budget is also inherently asymmetric. SpaceX can put larger antennas and more power on its satellites, but it cannot change the antenna, transmit power, or battery constraints of an ordinary smartphone. Consequently, satellite connectivity can potentially eliminate many of the world’s remaining coverage gaps, but it is much harder to see satellites economically absorbing the enormous traffic generated in dense urban and suburban areas.

In other words, geographic coverage is SpaceX’s advantage while capacity density remains terrestrial RAN’s advantage. This is also why SpaceX’s terrestrial ambitions matter. If Musk wants more than coverage—if he ultimately wants a meaningful share of total mobile traffic, here defined to include humans and machines operating indoors and outdoors—he will undoubtedly need terrestrial radios as well.

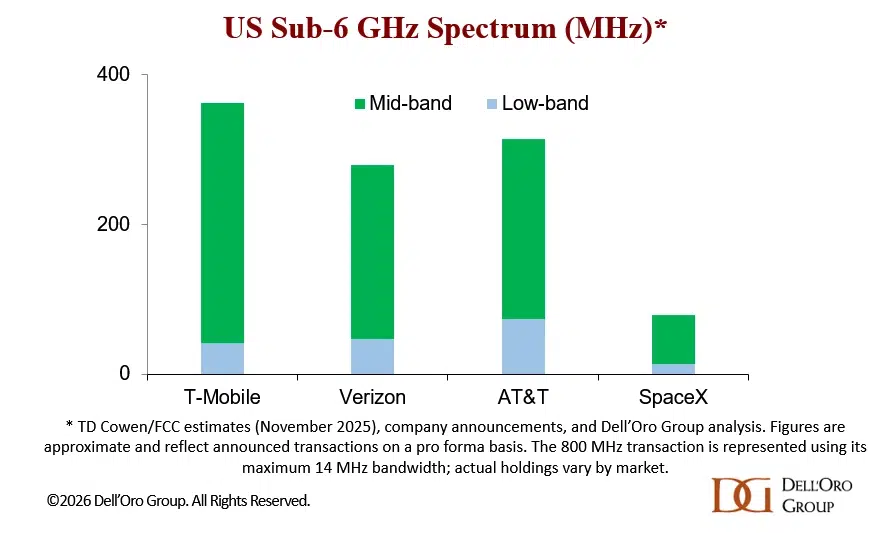
That leads to the second challenge: spectrum and terrestrial infrastructure. SpaceX’s spectrum acquisitions materially improve its position, but building a competitive mobile network requires more than owning some spectrum and small cells. The incumbent MNOs have spent decades accumulating spectrum across multiple bands and deploying hundreds of thousands of macro sites engineered around propagation, capacity, interference, mobility, and indoor coverage. SpaceX is exploring whether it can address this cost structure differently, potentially deploying large numbers of small base stations alongside existing Starlink terminals and using the Starlink network for backhaul.

The recent agreement to acquire 800 MHz spectrum is an important step toward addressing the spectrum challenge. Low-band spectrum offers favorable propagation characteristics and indoor penetration, making it well suited for providing broad geographic coverage and basic connectivity. However, the amount of spectrum involved is relatively limited and would not, on its own, provide sufficient capacity to support the traffic requirements of a nationwide mobile network at scale. While the acquisition strengthens SpaceX’s terrestrial ambitions, additional spectrum and infrastructure would be needed to compete more directly with established mobile operators, particularly in capacity-intensive markets.

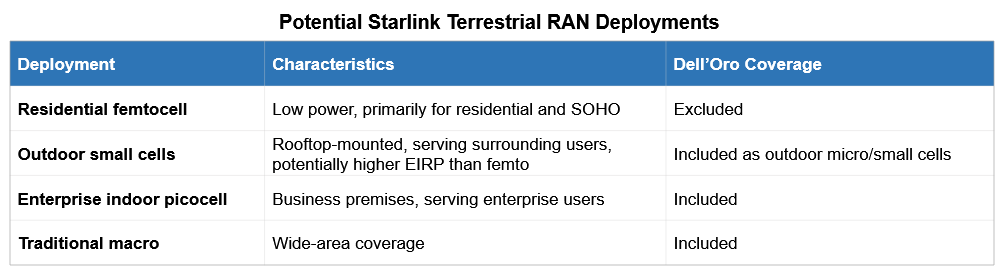
Beyond spectrum, the proposed small-cell deployment model is interesting because it could complement existing macro networks and potentially improve coverage and capacity in selected locations. Leveraging its existing Starlink footprint could reduce some of the costs and complexity of building a terrestrial network. However, questions remain about the practical economics, coverage, and scalability of this approach. While it is early days and we haven’t had a chance to talk to Starlink about this concept yet, one challenge could be overlap—Starlink terminals are currently located where customers need satellite broadband, not necessarily where a mobile network needs capacity. In addition, they still need to figure out RF planning, indoor coverage, handovers, and interference—these steps don’t disappear just because the ratios between small cells and macros change. Spectrum itself remains scarce and heavily regulated. Ultimately, the deeper SpaceX moves into terrestrial mobile, the more it will face the same physical, regulatory, and economic constraints that have shaped the traditional mobile infrastructure market.

The ecosystem is another major challenge. Incumbent operators already have the spectrum, sites, fiber, customers, devices, distribution, roaming relationships, regulatory infrastructure, and operational experience to deliver mobile service at scale. They can also respond collectively, whether through standards, roaming arrangements, spectrum partnerships, or alliances with competing satellite providers. Mobile connectivity involves far more than transporting bits—authentication, seamless mobility, voice, emergency services, device certification, billing, customer support, and roaming all need to work reliably. Regulation could also impact Starlink’s ability to operate a mobile network in some countries.

None of these challenges suggests that SpaceX cannot become a meaningful force in mobile connectivity. But they do suggest that replacing the terrestrial mobile network is a very different proposition from complementing it. Satellites give SpaceX an enormous structural advantage in geographic coverage, while the terrestrial incumbents retain an equally important advantage in capacity density, spectrum depth, infrastructure, and ecosystem. The more interesting question, therefore, may not be whether SpaceX can replace the MNOs or terrestrial RAN. Ultimately, the key question is how far they can go with their existing assets and how much further they want to go – where is the sweet spot?


Impact on RAN

From a RAN equipment perspective, SpaceX’s growing terrestrial ambitions add another potential demand driver. However, the magnitude remains uncertain. SpaceX has discussed deploying large numbers of small base stations alongside Starlink terminals, while its recent 800 MHz acquisition raises the possibility of a broader terrestrial coverage network. Some of these deployments could fall within our RAN market estimates, which include outdoor microcells and enterprise and public-access picocells but exclude residential femtocells. Even if some Starlink radios qualify as outdoor small cells, the incremental equipment opportunity could remain relatively modest compared with the global RAN market. However, if SpaceX ultimately expands beyond small cells into a broader macro RAN deployment, this could introduce some upside to the North American RAN outlook toward the latter part of our five-year forecast period, though the impact on the global market would likely remain limited.

The potentially more significant impact could be indirect. SpaceX could capture a meaningful share of connectivity revenues without carrying a corresponding share of mobile traffic, particularly as it expands beyond satellite coverage into terrestrial mobile services. If this increases competitive pressure on incumbent mobile operators, it could also weigh on their revenues and capital spending over time. This remains a longer-term risk rather than a change to our current forecast assumptions. For now, we are maintaining our five-year RAN outlook, including our assumptions for the terrestrial and non-terrestrial traffic split. While SpaceX’s ambitions are becoming clearer, the scale, timing, and economics of its terrestrial deployments remain uncertain.

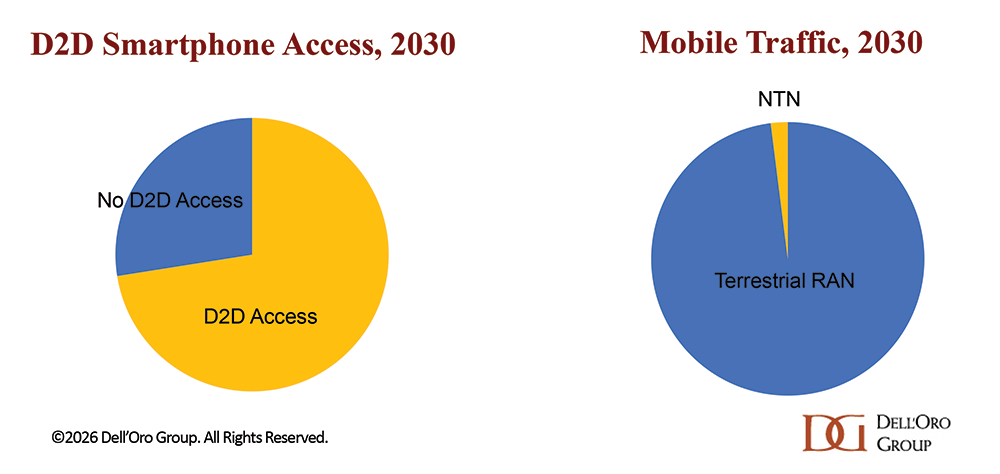
In other words, our long-term position remains unchanged—we continue to believe that NTNs are highly important complements to today’s terrestrial RAN networks and the future is hybrid. But we need to separate the “addressable D2D smartphone opportunity” from the “addressable mobile traffic share.” The base case is that D2D will scale rapidly and most smartphones outside of China will eventually have access to satellite D2D connectivity. At the same time, physics won’t change. And since the base case is that mobile traffic (human plus machine) will grow at a 17% CAGR over the next five years, with human-driven traffic still dominating (Ericsson Mobility Report), the mid-point scenario is for terrestrial RAN to carry more than 98% of the overall global mobile traffic by 2030.

There is also a question of time horizons. Our five-year RAN outlook is unlikely to capture the full implications of Musk’s connectivity ambitions, which appear to extend well beyond 2030. If autonomous vehicles, humanoid robots, and other forms of physical AI eventually scale as Musk envisions—he has discussed the potential for 10 billion humanoid robots by 2040—the connectivity requirements and economics could look very different. While the timing and magnitude remain highly uncertain, SpaceX’s longer-term ambitions could ultimately have a more significant impact on the mobile ecosystem than is reflected in our current five-year RAN outlook.

Alternative outcomes are likely, especially if we extend the forecast horizon. Two significant swing factors include the mobile traffic share of physical AI/machines in outdoor settings and the reach of Starlink’s terrestrial ambitions.

If physical AI accelerates faster than expected and traffic patterns/profiles are more conducive to satellite connectivity, the overall NTN share could surprise to the upside.  Similarly, if Physical AI develops more slowly than expected, the traffic split between terrestrial and NTN could differ.

The physics favor terrestrial RAN for capacity and NTN for geographic coverage, and that won’t change. But Musk has a history of changing the economics around the physics. The more consequential impact on RAN may ultimately come not from SpaceX’s equipment purchases, but from how its growing presence reshapes the economics of the operators investing in terrestrial networks.